
Tags
Financial Systemic Issues: Booms and Busts - Central Banking and Money - Corporate Governance - Cryptocurrencies - Government and Bureaucracy - Inflation - Long-term Economics - Risk and Uncertainty - Retirement Finance
Financial Markets: Banking - Banking Politics - Housing Finance - Municipal Finance - Sovereign Debt - Student Loans
Categories
Blogs - Books - Op-eds - Letters to the editor - Policy papers and research - Testimony to Congress - Podcasts - Event videos - Media quotes - Poetry
Adam, Eve, the snake and the fall of Fannie Mae and Freddie Mac
Published in Housing Finance International Journal.
September 6, 2026, marks the 18th anniversary of the failure of the U.S. housing finance giants, Fannie Mae and Freddie Mac, the government-sponsored enterprises that had previously characterized their own role as “the envy of the world.” On September 6, 2008, they were both put into conservatorship by the U.S. government. How could this have happened to two such prominent, powerful and politically-connected mortgage companies? The Book of Genesis helps us understand this instructive event: Running up the leverage is the snake in the housing finance Garden of Eden. It is a constant set of alluring temptations to enjoy the fruit of increased risk in the medium term, while setting ourselves up for the inevitable fall.
Let us begin with this famous painting by Lucas Cranach:

The woman is Fannie Mae. The man is Freddie Mac. The snake is whispering, “If you just run up the leverage of the whole U.S. housing finance system, you will become powerful and rich.” Fannie and Freddie are about to eat the apple of risk, which will indeed make them very powerful and very rich for a time, after which they will be shamed, humiliated and punished.
Fannie and Freddie were at the centre of the great American house price bubble and its subsequent collapse played out during the first decade of the 21st century. Bubbles in housing finance have occurred in many countries and times. They always end painfully, yet they keep happening. As the prophet said (slightly amended), “There is nothing new under the financial sun. The cycle that hath been, it is that which shall be.” Why is this?
In this context, consider this quotation: “The banking failures for the current year have been numerous, greatly aggravated by the collapse of unwise speculation in real estate.” What year was that? It could have been 2008, to be sure, but it is actually from 1891, as the then-U.S. Comptroller of the Currency looked sadly at the wreck of many of the banks of his day.
Some people say the problem is that housing lenders who go broke need to be personally punished, to get their incentives right. Economists are big, not without reason, on worrying about economic incentives. But a bigger problem is that it is so hard to know the future. Housing lenders don’t create housing finance collapses on purpose, but by mistake.
The city of Barcelona in the 14th century decided to manage the incentives of bankers by decreeing that those who defaulted on their deposits would be subject to capital punishment. And as one financial history tells us, “In 1360, Francesch Castello, a failed banker, was beheaded in front of his bank.” But this did not stop banks from failing.
One of the most important reasons that housing finance bubbles are so hard to control is that they make nearly everyone happy while they last. Who is making money from a housing finance bubble? Almost everybody. This is why the experience of a housing bubble is so insidious.
For example, take the experiences of Americans in the new 21st century. For a long time—the seven years of 2000-2006—the housing finance bubble generated profits and wealth. A lot of profits and wealth turned out to be illusory in the end, but at the time much of it was real and all of it seemed real.
As house prices rose, borrowers made more money if they bought more expensive houses with the maximum amount of leverage. Property flippers bought and sold condominiums for quick and repetitive profits, even if no one was living in them. Housing lenders had big volumes and profits. Their officers and employees got big bonuses. Numerous officers of Fannie Mae and Freddie Mac made more than $1 million a year each.
Real estate brokers had high volumes and big commissions. Equity investors saw the value of their housing-related stocks go up. Fixed income investors all over the world enjoyed the returns from subprime mortgage-backed securities which had investment grade ratings, and from Fannie Mae and Freddie Mac securities which seemed to be, and actually were, guaranteed by the U.S. government.
Most importantly, the 75 million households that were homeowners saw the market price of their houses keep rising. This felt like, and was discussed by economists as, increased wealth. Of course, this was politically popular. The new equity in their houses at then-market prices allowed many consumers to borrow on second mortgages and home equity loans, so they could spend money they had not had to earn by working.
The Federal Reserve Chairman of the time, Alan Greenspan, smiled approvingly on this housing “wealth effect,” which was offsetting the recessionary effects of the collapse of the previous bubble in technology stocks, which had turned into bust in 2000.
Home builders profited by a boom in new building. Local governments got higher real estate transactions taxes and greater property taxes, which reflected the increased tax valuations of their citizens’ houses. They could increase their spending with the new tax receipts.
The investment banks which pooled mortgages, packaged them into ever more complex mortgage-backed securities, and sold and traded them, made a lot of money and paid big bonuses to the members of their mortgage operations, including the former physicists and mathematicians who built the models of how the securities were supposed to work.
Bond rating agencies were paid to rate the expanding volumes of mortgage-backed securities and were highly profitable. Bank regulators happily noted that bank capital ratios were good, and that zero banks failed in the U.S. in the years 2005 and 2006—the very top of the bubble. In the next six years, 468 U.S. banks would fail.
The politicians trumpeted and took credit for the increasing home ownership rate, which the housing finance bubble temporarily carried to 69%, before it fell back to its historical level of 64%. The politicians pushed for easier credit and more leverage for riskier borrowers, which they praised as “increasing access” to borrowing. The snake had been whispering to the politicians, too.
The bubble was highly profitable for everybody involved—as long as the house prices kept going up. As long as house prices rise, the more everybody borrows, the more money everybody makes. This general happiness creates a vast temptation to keep the leverage increasing at all levels. But in 2006, the national average prices started going down, kept going down through the crisis of 2007-2009, and did not bottom until 2012.
This brings us to two essential questions.
The first is: What is the collateral for a mortgage loan?
Most people answer, “That’s easy—the house.”
But that is not the correct answer.
The correct answer is: Not the house, but the price of the house. The only way a housing lender can recover from the property is by selling it at some price.
The second key question is: How much can a price change?
To this question the answer is: A lot more than you think. It can go up a lot more than you expected, and it can then go down a lot more than you thought possible. It can go down a lot more than your worst-case planning scenario dared to contemplate.
So, the temptations of housing finance bubbles generate mistaken beliefs about how much prices can go down. American housing experts knew that house prices could fall on a regional basis, but most were convinced that house prices would not fall on a national average basis. Of course, now we know they were wrong, and that national average house prices fell by 30%. And they fell for six years.
By then, Fannie Mae and Freddie Mac had been banished from their pleasant housing finance Garden of Eden. Here they are, being sent into government conservatorship, as depicted by Michelangelo:
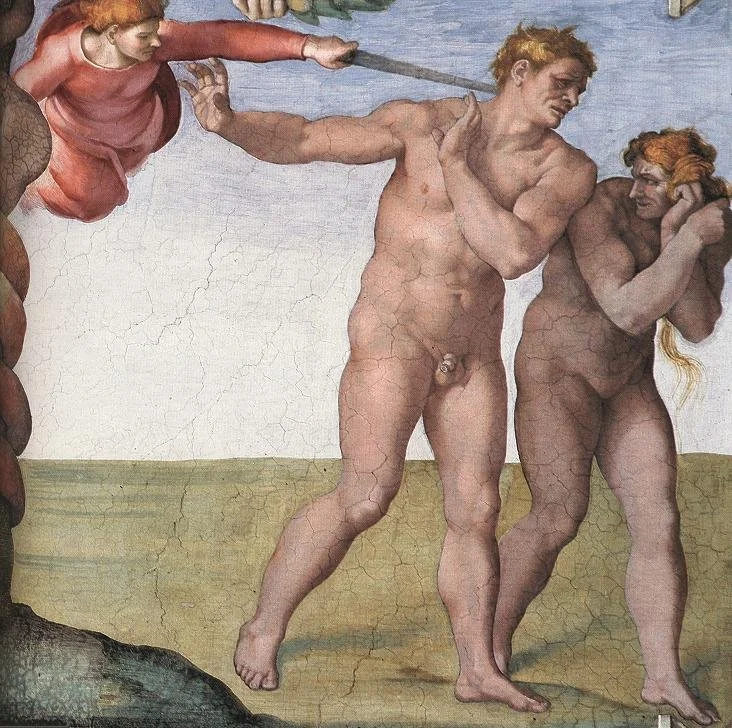
In conservatorship they remain to this very day, 18 years later. Having played a key role in running up the leverage of the whole system, they had suffered a fall they never thought possible, although it was well deserved.
Unlocking the Value of Low-Rate Home Mortgages
Published in RealClear Markets with Paul Kupiec.
Today, many homeowners considering a move face the prospect of replacing their low-interest rate mortgage of perhaps 3-percent with a new mortgage with a rate over 7-percent. Earlier this year, we published an idea that would allow homeowners to finance their move by unlocking the value of their below-market rate mortgage. The article generated a flurry of comments that said it wasn’t feasible, but we have since discovered that this idea has become reality. In April, Businesswire reports that Great Lakes Credit Union (GLCU) closed the first transaction in a new program that returns tens of thousands of dollars to homeowners selling their home and defeasing their low-rate mortgage.
The technique used to release the value of a below market rate debt contract is called “defeasance” and it is not a new idea. Municipalities have used it for decades—but it is new to residential mortgage finance.
In a defeasance transaction, the borrower posts US government securities as collateral with a licensed trust or escrow agent. The government securities must generate the cashflow needed to make timely payments of interest and principal on the debt being defeased. The trust or escrow agent uses the Treasury collateral to make the required loan payments. Generally accepted accounting principles recognize financial defeasance as a legal means of debt repayment [FASB 76, APB Opinion No. 26].
When we first floated the idea of residential mortgage defeasance, we thought that it might require legislation and that it would exclusively benefit borrowers. The GLCU program discussed below shows that we were wrong on both accounts.
A hypothetical example illustrates how defeasance monetizes the value of an existing below-market rate mortgage. A household is selling a home with a below-market rate mortgage. They purchased the home 5-years ago by borrowing $500,000 using a fixed-rate mortgage with an interest rate of 3-percent. After making 60 payments, their remaining mortgage balance is $444,532. Their monthly principal and interest payments are $2,108.
To make things simple, assume that Treasury securities yield 5 percent for all maturities. With Treasury rates at 5 percent, for $360,598 it will be possible to purchase Treasury strip securities that produce exactly the cashflows needed to make the remaining 300 monthly mortgage payments of $2,108 per month on time and in full.
A standard mortgage contract has a “due-on-sale clause” that requires the borrower to pay the mortgage loan balance of $444,532 upon sale of the house. If instead, the mortgage lender allows the borrower to defease the remaining mortgage payments, the borrower would use the proceeds from their home sale to buy the aforementioned Treasury securities for $360,598 and pledge them as collateral to a qualified trust or escrow agent. The trust uses the cashflow from the pledged Treasury securities to make all 360 remaining mortgage payments. Before transactions costs, defeasance unlocks $83,934 in value ($444,532-$360,598) that can be shared between the borrower and lender.
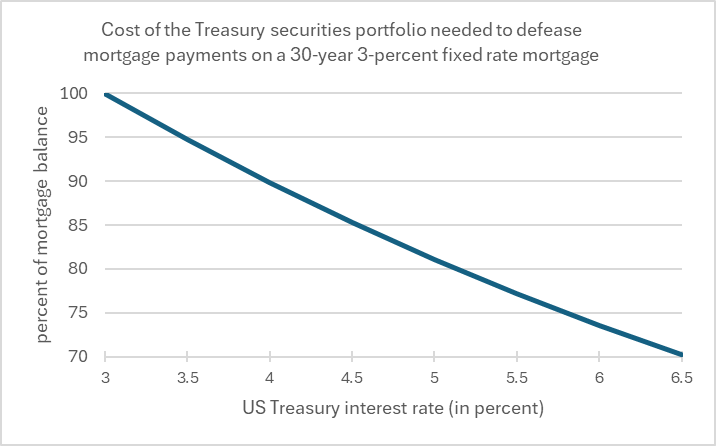
The following graph shows the cost of a Treasury securities portfolio, measured as a percentage of the remaining mortgage balance, that is required to defease the remaining 360 monthly mortgage payments on the 30-year 3-percent fixed rate mortgage for different levels of Treasury interest rates. The calculations assume the Treasury yield curve is flat for every rate level. The graph shows that defeasance unlocks a substantial share of the remaining mortgage balance at current Treasury rates.
The GLCU program shows that, when we first proposed this idea, we missed two critical points: (1) with an acceptable mortgage marketing and financial incentive, a lender can voluntarily agree to defeasance; and (2), defeasance is already a completely legal way to discharge a borrower’s debt payment obligation if the lender agrees.
For a lender holding a mortgage loan, including a bank or credit union, a defeased mortgage remains valued at amortized cost, exactly as before. Defeasance does not create an accounting loss. The institution recognizes principal and interest payments over time as they are paid by the defeasance trust, exactly as if the homeowner continued making payments. Moreover, because the mortgage will be collateralized by risk-free government securities instead of real estate, the loan will be eligible for reduced regulatory capital treatment [12 CFR §217.37(b)(3)(iii)(B)].
In the GLCU program, the lender receives compensation for agreeing to defeasance. In practice, the monetized defeasance value—$83,934 less transactions costs in our example—will be shared between the borrower and the lender, with the exact split a matter for negotiation.
Residential mortgage defeasance is not just a theoretical idea, it is a real option for existing homeowners with below market rate mortgages held by portfolio lenders. Should banks, credit unions, and savings institutions embrace this option—an option that benefits both lenders and their customers—mortgage defeasance will help reduce the lock-in effect now plaguing the housing market.
Paul H. Kupiec is a senior fellow of the American Enterprise Institute. Alex J. Pollock is a senior fellow of the Mises Institute. The authors have no financial interest in or relationship with GLCU.
Americans Increasingly Priced Out of Buying Homes, Thanks to the Federal Reserve’s Manipulation of Mortgage and Housing Markets
Published in The New York Sun.
The unaffordability of houses for many American households is a key problem in both politics and economics. How did American house prices get so high? A central culprit is the Federal Reserve’s vast manipulation of the mortgage and housing markets.
Between the founding of the Fed in 1913 and 2008, the amount of mortgage assets on the Fed’s balance sheet was exactly zero. The amount of mortgage assets the Fed should in principle own is zero. The classic Fed knew that its money-printing monopoly should not be used to subsidize or finance any particular economic sector, including housing.
Yet under the pressure of the deflating housing bubble in 2008, under the leadership of Chairman Ben Bernanke, the Fed started the unprecedented gamble of buying mortgage assets. These were primarily mortgage-backed securities issued by Fannie Mae and Freddie Mac.
As part of this program the Fed, knowing that its MBS investments might result in losses, unilaterally changed its accounting presentation to hide the reduction in its capital that losses, which did indeed ensue, would cause.
The goal was to drive down the interest rates on mortgages and pump up the price of houses. The Fed promised that this was a purely temporary, emergency program which would be reversed when the crisis was over.
This promise was not kept. It is now 18 years since the Fed’s MBS buying started, 17 years since the financial panic ended in 2009, and 14 years since American house prices bottomed in 2012. The Fed kept buying MBS, suppressing mortgage interest rates to abnormally low levels and thereby inflating house prices, until March 2022, when its MBS portfolio reached $2.7 trillion. That alone was three times what the total assets of the Fed were at the end of 2007. Today the Fed still owns MBS of $1.9 trillion.
As central to understanding American housing policy, we must remember that the housing finance system has collapsed twice in living memory — once in the 1980s and again in the 2000s. It has also produced two housing price bubbles in the first quarter of the 21st century. The first peaked in 2006, and ended with the financial crisis of 2007-2009. We are still in the late stages of the second, with home price deflation looming ahead.
America’s double house-price bubble is remarkable. National average house prices now are far above the peak of the first bubble. The S&P Cotality Case-Shiller National House Price Index hit its previous peak in mid-2006 at 184.6. In mid-2026, it has climbed to 336.7— 82 percent higher than the top of the first bubble.
If we adjust for the accumulated rise in the Consumer Price Index over these two decades, house prices are now 10 percent above the previous bubble peak in real terms. One informed estimate is that they are now about 30 percent higher than their long-term trend.
We can principally thank the Federal Reserve for these exaggerated house prices, brought on by its artificial suppression of 30-year mortgage interest rates to less than 3 percent, enforced by its buying that portfolio of $2.7 trillion of MBS with newly-printed money.
When the Fed was still buying in 2022, it was long after house prices were obviously in a runaway asset price inflation. It was at the time and remains very hard to understand this behavior of the Fed.
Once mortgage interest rates went back to their historically normal levels of 5 percent to 7 percent, the Fed had rendered the inflated prices of houses unaffordable for many Americans. This experience demonstrates yet again how misguided is the idea that the Fed should be “independent” of the legislature, and how necessary it is for Congress to establish effective accountability for it.
The median price for existing home sales in July 2026 was $431,400, according to the National Association of Realtors. To add some historical interest, here is an advertisement for a ranch house from 1955 that we now find hard to believe:
“3 BEDROOMS, ONE BATH, SCREENED PORCH: TOTAL PRICE $7,900. Monthly payments including principal, interest, taxes and insurance, $49.74.”
Of course we are not going back there, but I believe an unavoidable result of the Fed-induced second house price bubble of this century is that house prices will again fall on a national basis. National house price indexes are now falling in inflation-adjusted terms by about 2 percent per year and in many places average prices are dropping in nominal dollar terms. National average prices for newly-built houses are down 14 percent from their peak in 2022.
Though not without pain for some who bought at the top, the arrival of falling house prices will improve affordability for home buyers in general.
Letter: Bagehot’s bubble warnings describe Evergrande today
Published in The Financial Times.
Hui Ka Yan, the boss of Evergrande in the heady days of the vast Chinese real estate bubble, and China’s richest person in 2017, has now been sentenced to life imprisonment for fraud and other financial crimes. But he is far from the first of the type (“Evergrande founder jailed for life and assets seized,” Report, August 21). As Walter Bagehot pointed out in his classic book Lombard Street more than 150 years ago, fraud and bubbles go together.
“The good times of too high price almost always engender much fraud. All people are most credulous when they are most happy; and when much money has just been made, when some people are really making it, when most people think they are making it, there is a happy opportunity for ingenious mendacity. Almost everything will be believed for a little while.”
Just as today’s investors believed in those “billions of dollars in international bonds”, now worth pennies on the dollar, that they bought from Evergrande.
Letter: The Fed Is Not a 'Market Maker of Last Resort
A shortened version of the letter was published in The Wall Street Journal.
James Mackintosh suggests that central banks, including the Federal Reserve, made the switch in financial crises from being "the lender of last resort" to "also being market makers of last resort" (Central Banks Are Stuck in a Cycle of Crises," August 17). It is true that they made a momentous switch, but that was not it. The Fed and the others became not market makers, but leveraged buy and hold investors of last resort, a completely different thing. A market maker is constantly buying and selling. The Fed was only buying, not selling, in order to push up the price of the securities and to drive down their yields. A market maker is in it to make money on the bid-asked spread; the Fed created giant leveraged naked long positions that might, and then did, lose vast amounts of money. The Fed generated operating losses of more than $200 billion and in addition mark-to-market losses of more than $800 billion, for an economic loss of more than $1 trillion. Being a leveraged buy and hold investor of last resort can be an expensive proposition.
ALEX J. POLLOCK
Mises Institute
Lake Forest, Ill.
Testimony to the Financial Services Committee on Promoting Housing Affordability
Testimony of
Alex J. Pollock
Senior Fellow, Mises Institute
To the Committee on Financial Services
U.S. House of Representatives
Hearing on “Strengthening the American Economy:
Promoting Growth, Opportunity, and Prosperity”
September 2, 2026
Promoting Housing Affordability
Mr. Chairman, Ranking Member Waters, and Members of the Committee, thank you for the opportunity to be here today. I am Alex Pollock, a senior fellow at the Mises Institute, and these are my personal views. My more than five decades of work in banking and on financial policy issues have included many years of involvement in the practice and the policy issues of housing finance, as well as in the related studies of the evolution of financial systems, central banking, cycles of booms and busts, risk and uncertainty, and the interaction of banking and politics. I previously served as the Principal Deputy Director of the Office of Financial Research of the U.S. Treasury, a fellow of the American Enterprise Institute, and president and CEO of the Federal Home Loan Bank of Chicago, and am the author of three books in the field, with a new one, Adventures in Political Finance, forthcoming.
The 21st Century ROAD to Housing Act is a truly bipartisan combination of actions reflecting “years of bipartisan, bicameral collaboration,” as Chairman Hill has said—not to mention the art of compromise. This is manifest in the impressive voting majorities it garnered in the House and Senate (358-32 and 85-5). I think it is a fair summary to say that the Congress heard the American people’s unhappiness with the unaffordability of housing and responded in this act with multiple reforms to reduce regulatory costs and increase the supply of housing. This strategy favorably contrasts with many past efforts to expand the subsidized financing of houses to increase demand, for example by expanding Fannie Mae and Freddie Mac or the Federal Reserve’s purchases of mortgage-backed securities, which efforts get capitalized in sellers’ markets into house prices, pushing the prices ever higher.
Regulatory Reform
Among the act’s reforms, especially notable is the reduction of burdensome, costly or outmoded regulations. As the AEI Housing Center writes, the act “eliminates an expensive requirement to build manufactured housing on permanent steel frames, streamlines environmental reviews, and incentivizes cities to provide preapproved home designs, which will simplify things for governments, regulators and builders;” and as Pew Charitable Trusts says, the legislation “contains dozens of provisions designed to speed up housing production and lower costs.” I believe the manufactured housing provisions in particular offer the possibility of materially improved affordability.
The most-strongly expressed conclusion on this aspect of the act is provided by Jared Bernstein, chairman of the Council of Economic Advisors under President Biden, and Jim Parrott, a senior housing advisor in the Obama administration. “The law will break through,” they write, “a lot of the regulatory sludge holding back the construction industry.” The “sludge,” to use their term, originated with good intentions and grew more complex and costly over time through natural bureaucratic evolution. This emphasizes the necessity for Congress regularly to review and update, as the act does, regulation that results in reducing affordability.
Community Banks
I was glad to see the community bank provisions of the act, which were added by the House and this Committee. The community banking sector is one of the distinguishing characteristics the American financial system, giving it a local presence and dispersed credit decision-making, and therefore a systemic role in promoting opportunity.
There are by the FDIC’s count, now 3,818 community banks, or approximately 90% of all U.S. insured banks and savings institutions. The number of community banks has dramatically fallen in recent decades; it is down by more than half from the 8,315 in the year 2000, for example. Helping maintain the vitality of this sector is a key goal.
An important provision of this title of the act is encouraging the chartering of new banks. While new entry is always desirable, I believe this is especially relevant in times of banking system troubles, when the system needs new capacity and new capital, unencumbered by past cyclical mistakes.
The act also mandates studies to improve the availability of small residential mortgages of under $100,000 (although previous generations would certainly have been surprised that we think a $100,000 mortgage is small), and whether federal regulations unintentionally inhibit these mortgages. In my view, these studies complement the community banking provisions.
I suggest that the reviews of small mortgages should consider what we discovered while I was at the Federal Home Loan Bank of Chicago: namely that the credit quality of residential mortgages made by local community banks and savings institutions was systematically better than the market averages, reflecting their local market and credit knowledge.
So why, Congress might ask, should these community mortgage lenders divest the credit risk of their own customers and their own loans to Fannie Mae and Freddie Mac, while paying a significant fee for doing so? My view is that it would be better for the housing finance system to have the holding of mortgage credit risk widely diversified among many lenders across the country than to have it concentrated in two giants on the banks of the Potomac. I believe this would be especially advantageous for community lenders, who know their own borrowing customers well.
Providing Houses for Rental
Title X, prohibiting purchases of houses by large institutional investors, is certainly the most controversial part of the act. The House and this Committee made it significantly less controversial, however, by making clear the continuing role of institutional investors in the provision of houses for rental markets through such programs as build-to-rent, renovate-to-rent, boosting homeownership through positive reporting of rental payments, and development of senior housing.
Many American households need or prefer rental houses rather than apartments or purchased houses. Military families who must often move to new assignments are readily cited as an important and clear example. In my opinion, houses rented either by necessity or preference, should be an available competitive option in the housing market. This is consistent with the various permissible categories detailed in Section 1001(a )(2).
Central Bank Digital Currency
Title XI of the act prohibits the Federal Reserve from creating a central bank digital currency (CBDC) through 2030, adding that any decision to issue a CBDC would require “authorization by an Act of Congress.”
In my opinion, this is an excellent provision. In 2018, I testified to the Subcommittee on Monetary Policy and Trade of this Committee that “to have a central bank create digital currency is a terrible idea—one of the worst financial ideas of recent times.” This is still my opinion. Having a CBDC would make the Fed an overwhelming credit allocator for the economy, a power which would inevitably be politicized. Moreover, a CBDC would give the Fed and the government oppressive potential for spying on American citizens.
I believe that Title XI is an exemplary model of the Congress exercising its Constitutional Article I Money Power, carrying out proper oversight, and ensuring the accountability of the Federal Reserve to the elected representatives of the People.
In Sum
Considering the act overall, and the leadership displayed by this Committee, we have advanced toward greater housing affordability in numerous ways.
ADDENDUM
Further Context on Housing Affordability
In the wider context of the act, it goes without saying that house prices are key to affordability and housing opportunity.
As central to our perspective on housing policy, we should remember that the U.S. housing finance system has collapsed twice in living memory--once in the 1980s and again in the 2000s. It has also produced two massive house price bubbles. The first began inflating in 1999 and ended with the financial crisis of 2007-2009. We are still in the late stages of the second. This U.S. double bubble in 21st century house prices makes dramatic graphs, with house prices now far over the peak of the first bubble. The Case-Shiller National House Price Index peaked in mid-2006 at 184.6. Now it is at 336.7. In real terms, adjusted for ongoing general inflation for 20 years, house prices on this index are currently more than 10% over the peak of the first bubble. One estimate is that they are 30% over their long-term trend.
In my opinion, we can principally thank the Federal Reserve for these exaggerated house prices, brought on by its extreme suppression of 30-year mortgage interest rates to less than 3%, enforced by its unprecedented buying of $2.7 trillion of mortgage securities with newly-printed money. The Fed kept buying until March 2022, long after house prices were in an obvious bubble. Once mortgage interest rates went back to normal levels of 6% or so (the average rate being 6.66% at this point, according to Freddie Mac), the Fed had rendered houses unaffordable for a great many Americans. I believe this experience emphasizes the need for Federal Reserve accountability to Congress.
The median existing-home price for July 2026 was $431,400, according to the National Association of Realtors. In looking for historical contrast, I found this advertisement for a ranch house from 1955, which you may enjoy:
“3 BEDROOMS, ONE BATH, SCREENED PORCH: TOTAL PRICE $7,900. Monthly payments including principal, interest, taxes and insurance, $49.74.”
An unavoidable result of the second house price bubble of the century, in my opinion, is that house prices must and will fall on a national average basis. The national house prices indexes of the AEI housing Center and of Case-Shiller are already falling in inflation-adjusted terms by about 2% a year, and I believe reductions in nominal terms will follow. Average prices for new houses are already down 14% from their peak in 2022, according to Census Bureau data, not including the cost of the mortgage-rate buydowns being provided.
Falling prices will improve affordability, though not without pain for some who bought at the top with high leverage.
Residential Loan Defeasance
Finally, an important and much-discussed affordability problem of the housing market of our time is the “lock in” effect, where because potential sellers don’t want to give up their existing cheap mortgages, the supply of houses for sale is restricted, reducing affordability for others. Paul Kupiec of AEI and I early this year explored the possibility of applying a classic debt management tool, namely defeasance, to residential mortgages, to help address this widespread housing problem.
We were pleasantly surprised to discover recently that one company has developed a structure to implement the residential mortgage defeasance concept that has been introduced to the market to address “locked-in” mortgages and houses. It appears to work with lenders that hold the loans in portfolio. I believe this is quite an interesting housing finance development the Committee may wish to review.
Thank you again for the opportunity to share these views.
Letter: The Fed’s seigniorage is also under attack
Published in the Financial Times.
Ignazio Angeloni writes that “tokenised deposits look more promising” than stablecoins (“Stablecoins or tokenised deposits? The jury’s out”, Letters, July 31).
If a tokenised deposit can stay in circulation, making payments for an indefinitely large series of transactions, it has become the functional equivalent of paper currency issued by private banks. This was historically a key business of private banks but got monopolised by central banks — in the US case, by the Federal Reserve. Perhaps its monopoly will be broken?
Stablecoins are also competitors with the Federal Reserve, especially competing with the Fed’s $100 bills used around the world for informal (or illegal) payments.
Thus both banks with tokenised deposits and stablecoin issuers become competitors to the Fed.
Issuing currency — via seigniorage — is by far the most profitable activity of central banks, generating profits for the Fed of about $88bn a year at current interest rates. How much of this profit could be captured by private issuers as the Fed’s circulating currency monopoly faces competition?
What Currency Would Americans Choose?
In which our columnist questions his readers.
Published in The New York Sun.
In the spirit of the Declaration of Independence, let us ask whether the rights to “life, liberty and the pursuit of happiness” should include the right to use the money of your and your counterparties’ own choice. Or should you be forced to use the paper dollars which the Federal Reserve prints?
Under present circumstances one is forced to use what we call Federal Reserve Notes, because the government grants a complete monopoly in money to the Fed. We are so accustomed to this situation that we are likely to take it for granted. Yet it is not necessary that the Fed have the power to print as much money as it wants to print.
Or to lend as much as it wants to the government to spend. Or to create perpetual inflation, impose a constant inflation tax on the people without any approval by the Congress, and constantly depreciate the money, savings, and wages to finance the government’s deficits.
The philosopher-economist, Friedrich Hayek, put the question in his “Choice in Currency: A Way to Stop Inflation.” That was issued in 1976, two years after Hayek won the Nobel Prize in Economics. “Why,” Hayek asked, “should we not let people choose freely what money they want to use?” He understood that the Treasury and the Fed would hate this question, but a free people ought to take it up.
Hayek suggested that the key problem is not that the Federal Reserve gets to issue money, but that it gets a monopoly in doing so. He proposed that this monopoly be taken away, so that the Fed could still issue money, but the money it creates would have to compete with other money for the public’s confidence.
In Hayek’s proposed world, central banks would be disciplined by this competition in currency. “There could be no more effective check against the abuse of money by the government than if people were free to refuse any money they distrusted and to prefer money in which they had confidence.” Have governments abused their money power? Without doubt.
Hayek warned that nearly all governments “used their exclusive power to issue money in order to defraud and plunder the people.” His thoughts are congenial to those who want cryptocurrencies to compete with Federal Reserve notes. In 2025, Congress enacted with bipartisan majorities the “Genius Act,” favorable to the cryptocurrency called stablecoins.
It would be newsworthy if stablecoins were an example of Hayekian choice in currency, but unfortunately, they are not. Because stablecoins are tied one-for-one by definition and now by law to Federal Reserve dollars, when the Fed is depreciating your paper dollars, it is equally depreciating your stablecoins.
However, there have been historical examples of true parallel currencies in America. The most pertinent case was during the Civil War, when as described by Joseph Salerno of the Mises Institute, pure paper Treasury greenbacks “swiftly became the domestic currency… but gold continued as a parallel currency in the East, because of its use in foreign trade.”
This precedent is consistent with Hayek’s proposal to create competition for central bank paper currencies, because Hayek was really thinking about gold. That the best monetary competition would come from gold is something about Hayek’s essay often not understood.
When the essay was published in 1976, it had been only two years since the United States government had at long last rescinded its oppressive 1933 law making it a criminal offense to own any gold to protect yourself against government monetary depreciation. This is a good example of the warning of Psalm 146: “Do not put your trust in princes” — or, Hayek would add, central banks.
Wrote Hayek, “Where I’m not sure is whether in such a competition for reliability any government-issued currency would prevail, or whether the preference would not be in favor of some such units as ounces of gold. It seems not unlikely that gold would ultimately re-assert its place… if people were given complete freedom to decide what to use as their standard.”
So I turn to my readers. Had they the freedom to choose the money they really wanted, what would it be? Would it be gold, or the Fed’s inflationist paper currency, or a cryptocurrency, or something else? Do they, like Hayek, think gold would win in a free competition?
July 28 Federalist Society event: The CLARITY Act and Fed Master Accounts: Defining Crypto's Place in the U.S. Financial System
Join us for a timely discussion on two developments shaping the future of digital assets in the United States. We will examine the CLARITY Act and its effort to establish clear rules for whether digital assets fall under SEC or CFTC oversight, as well as the ongoing dispute over Federal Reserve master accounts for crypto-focused banking institutions.
Together, these issues highlight a central question: will digital asset firms gain both regulatory clarity and meaningful access to the nation’s financial infrastructure? The webinar will explore how the interaction between market-structure legislation and banking access could influence stablecoins, institutional adoption, and the broader integration of crypto into traditional finance.
Opening Remarks
Hon. Cynthia Lummis, U.S. Senate, Wyoming
Featuring:
Paige Paridon, Executive Vice President and Co-Head of Regulatory Affairs, Bank Policy Institute
Alex Pollock, Senior Fellow, Mises Institute
Corey Then, Deputy General Counsel of Regulatory Strategy and Global Policy, Circle
Prof. David Zaring, Elizabeth F. Putzel Professor and Professor of Legal Studies & Business Ethics, The Wharton School, The University of Pennsylvania
[Moderator] J.C. Boggs, Partner, King & Spalding
The Map and the Bubble: A Review of Alan Greenspan’s ‘The Map and the Territory’
Originally published December, 2013.
The so-called “Great Moderation,” for which our fiat-currency central bankers gave themselves so much credit, turned out to be the Era of Great Bubbles. The U.S., in successive decades, had the Tech Stock Bubble and then the disastrous Housing Bubble. Other countries had real estate and government debt bubbles.
Presiding over the Era of Great Bubbles as Chairman of the world’s principal central bank from 1987 to 2006, was Alan Greenspan, a man of undoubted high intelligence and great talent with scores of subordinate Ph.D. economists to build models for him. He was then world famous as “The Maestro,” for supposedly being able to always orchestrate the macro economy to happy outcomes. The idea that anybody, no matter how talented, could really be such a Maestro is ridiculous, just as the idea that national house prices could never fall was ridiculous—but both were widely believed and expressed nonetheless.
The central bankers, working diligently for their concept of economic Moderation, presided over the Era of Great Bubbles. Is this coincidence? Or does the one cause the other?
Greenspan, in his highly interesting new book, The Map and the Territory (2013), muses:
The near quarter century from 1983 to 2007 was a period of very shallow recessions and seemingly extraordinary stability [aka “The Great Moderation”]. But protracted economic stability is precisely the tinder that ignites bubbles;1
and further: “Central banks have increasingly been confronted by the prospect that their success in achieving stable prices has laid the groundwork for asset price bubbles.”2
Let us begin by pointing out that the first part of the period Greenspan cites was not notable for financial stability. In the 1980s, the savings and loan industry infamously collapsed, taking its government deposit insurer (the Federal Savings and Loan Insurance Corporation) with it into irreparable insolvency. For the ten years from 1983 to 1992, 660 savings and loans failed. So did 256 savings banks, and so did 1,321 commercial banks. In all, this decade brought the failure of an appalling 2,237 U.S. financial institutions, an average of 223 per year for ten years. Oil and farmland bubbles collapsed in the 1980s, the government-sponsored Farm Credit Banks needed a bailout, numerous foreign governments defaulted on their debt to U.S. banks, and the early 1990s featured a massive commercial real estate bust.
All of the 1980s disasters represent the aftermath of the Great Inflation of the 1970s, when annual inflation rates got to double digit increases. This inflation was created by the Federal Reserve itself and its money printing exertions in the crises of those days. Greenspan provides a notable contemporary quote: “America is in the worst economic emergency since the Great Depression”—the date? 1975.3
In the next decade, with some success and by imposing a lot of pain, the Fed undertook “fighting inflation”—the inflation it had itself caused. Presumably the Fed learned from this experience. So in the 2000s it performed a variation: the Fed first stoked the asset price inflation of the Great Housing Bubble and then worked to bail out the Bubble’s inevitable collapse.
To evaluate the Fed accurately, we have to confront how the Fed relates to bubbles not only through “economic stability,” as Greenspan suggests (although that does indeed play an important psychological role in bubbles), but through its money printing and financial market manipulations. These can and do bring about asset price inflations.
Sometimes this is intentional on the part of the Fed, when it is trying to bring about “wealth effects,” as it did with the housing boom in 2001-2004 and is now doing again with of so-called “quantitative easing,” including its $1.5 trillion mortgage market manipulation. Exaggerated asset inflations always end badly, needless to say, but those highly leveraged with debt are the worst. This is why, as Greenspan correctly says, the Housing Bubble was so much more destructive than the Tech Stock Bubble.
Fiat-currency central banks like the modern Fed are, among other things, in the business of money illusion—that is, trying to influence real resource costs and prices by depreciating the currency they issue at more rapid or less rapid rates. The business of money illusion often turns into the business of wealth illusion: bubbles create illusory “wealth” that will evaporate.
In footnote 3 to his Introduction, Greenspan importantly observes, “I believe asset price causation is underrepresented in most models”4—he means macroeconomic forecasting models. He recognizes two problems here: the shortcoming of macroeconomic forecasting models, and the difficulty of knowing when asset price inflations become bubbles.
For example, “The model constructed by the Federal Reserve staff [recall those scores of economists], combining the elements of Keynesianism, monetarism, and other more recent contributions to economic theory, seemed particularly impressive.” But: “The Federal Reserve Board’s highly sophisticated forecasting system did not foresee a recession until the crisis hit. Nor did the model developed by the prestigious International Monetary Fund.”5
With admirable candor, Greenspan relates that at the onset of the financial crisis in August, 2007, “I was stunned.”6
In short, “leading up to the almost universally unanticipated crisis of September 2008, macromodeling unequivocally failed when it was needed most, much to the chagrin of the economics profession.”7
Why did the models which seemed so impressive perform like Casey at the Bat?
For one thing, “models, by their nature are vast simplifications.”8 True even for extremely complex models. Moreover, they do not deal so well with discontinuities, like the shriveling of prices in the collapse of bubbles and panics. And: “a related obstacle for forecasting and policy setting,” Greenspan reflects, “is that we seek to identify in advance which assets or markets could turn toxic and precipitate a crisis. It was not apparent in the early 2000s, as many commentators retroactively assume, that subprime securities were headed toward being the toxic asset they turned out to be.”9
This is fair. The senior-subordinated structures and techniques used to design these securities were viewed as a major financial innovation and a creative advance, which in fact they were. But innovations, which are the creators of long-term growth, also create uncertainty and surprises, good and bad.
Greenspan quotes the famous dictum of Joseph Schumpeter that economic growth depends on “creative destruction.”10 This is his only citation of Schumpeter, but he might have quoted that illustrious economic thinker at greater length to illuminate the problems of why models, sophisticated or simple, may fail at the most important times. For example, Schumpeter wrote (in 1946):
“The essential points about creative response are these…From the standpoint of the observer who is in full possession of all relevant facts”—say by hypothesis a Federal Reserve Chairman—“it can always be understood ex post; but can practically never be understood ex ante, that is to say, it cannot be predicted…. No deterministic credo avails against this.”11
Schumpeter considered “innovation, being discontinuous.” He sharply contrasted “the concept of equilibrium, the continuous curves and small marginal variations…the circuit flow of economic routine”—easier to model-- with a real “theory of capitalist change,” which requires “the type and function of the entrepreneur, which will…destroy any equilibrium that may have established itself,” producing “cyclical waves which are essentially the form progress takes.”12 This applies to financial, as well as industrial and commercial, entrepreneurs.
Dipping into some classic financial wisdom, Greenspan considers “the ephemeral nature of market liquidity,”13 and the human “propensities related to fear [and] euphoria.” When mass euphoria turns to panicked fear, market liquidity vanishes. He considers the propensity for “herding.” Here we should especially add the dangerous propensity for cognitive herding, which affects the thinking and expectations of all kinds of actors in a financial bubble, central bankers and regulators, as well as investors, bankers and borrowers. Then there is “optimism” which “encourages entrepreneurial initiatives” and “probably assures greater successes, but certainly more failures as well.”14 And not to be forgotten is the famous Greenspan phrase, “irrational exuberance.”
The collective optimism which helps induce bubbles tends to flourish during periods of prosperity, success and stability, as in the Greenspan quote above: “the tinder that ignites bubbles.” This thought echoes Hyman Minsky, the theorist of the endogenous build-up of “financial fragility,” whose work has been summarized as “Stability creates instability.” In slightly longer form, the logic is: stability creates optimism, optimism creates speculative debt, and speculative debt ultimately creates instability. However, Minsky’s insightful work on financial psychology and cycles is not mentioned in this book.
Neither is Frank Knight’s famous distinction between risk and uncertainty, although it seems highly relevant to the conundrums of economic forecasting and central banking. It will be recalled that in his famous 1921 book, Risk, Uncertainty and Profit, Knight proposed that the unknowable future is characterized not only by risk, but more importantly, by uncertainty. With risk in Knight’s sense, you cannot know the outcome, but you do know the odds—like rolling fair dice or flipping a fair coin. But with uncertainty, you cannot even know what the odds are, so your ignorance of the future is more radical. Knight thought that the essential function of the entrepreneur, and the source of all economic profit, was bearing uncertainty. In other words, uncertainty is at the heart of economic growth. In contrast, many financial models which failed in the mortgage bubble thought their essential function was to deal only with risk, that they knew the odds—needless to say, they didn’t.
Greenspan reasonably observes that “Having been mugged too often by reality, we forecasters appropriately express less confidence.” Considering “the vagaries of human nature, forecasting will always be somewhat of a coin toss”—to quibble about the metaphor, it would be better to have something expressing uncertainty, rather than risk, here. But we get the point. “Euphoria will always periodically produce extended bull markets that feed off herd behavior [and herd thinking], followed by rapid fear-induced deflation of the consequent bubbles.”15
In his concluding chapter, Greenspan poses a profound question. The enterprising market economy is “the most effective form of economic organization ever devised,” with the “remarkable gains in material well-being and life expectancy” which are obvious to all. Then the “but”: “But at its core is creative destruction.” (16) Can the amazing record of economic progress happen without accompanying booms and busts? Or are booms and busts inevitably entwined in the energies which create the progress?
Greenspan’s thoughtful answer: “I see no way of removing periodic irrational exuberances without at the same time significantly diminishing the average rate of economic growth and standards of living.” For “rising standards of living require innovators who have unlimited expectation of success and perseverance no matter how many times they fail…. Exuberance (the propensity for optimism) is required—even if at times it runs to excess.”16
All of us should ponder this, as well as pondering a further essential question which Greenspan, in spite of the many provocative ideas this book discusses, does not address. Do the constant efforts of central banks to promote moderation and stability, by money printing and interest rate manipulation, all the while facing ineluctable uncertainty, and using models which fail when most needed, result in making the booms and busts better or worse?
Originally published December, 2013. Republished with permission of the author.
1. p. 53
2. Ibid.
3. p. 133
4. p. 345
5. p. 7
6. p.37.
7. p. 7.
8. p. 5.
9. p. 51.
10. p. 93.
11. Joseph Schumpeter, The Economics and Sociology of Capitalism (1991), pp. 411-412
12. Schumpeter, Essays on Entrepreneurs, Innovations, Business Cycles, and the Evolution of Capitalism (1951), pp. 67, 69.
13. p. 92.
14. pp. 6, 32.
15. pp. 292-293.
16. pp. 299-300.
Update on Fannie Mae and Freddie Mac
Published with Edward J. Pinto in Housing Finance International Journal.
Since the fall of the American savings and loan industry four decades ago in the 1980s, U.S. housing finance credit has been dominated by the tightly government-connected firms of Fannie Mae and Freddie Mac. Until 2008, Fannie and Freddie were privately owned, privately managed companies, but they were always completely dependent on the guarantee they enjoy from the U.S. Treasury. They still are dependent on it and will continue to be. This guarantee now totals $7.6 trillion (that’s “trillion” with a “T”). It is not explicitly written down, but it is certainly a liability of the government; it is said by all to be an “implicit guarantee.” No informed person doubts that it is a real obligation of the government. We feel sure that that includes the officers of the U.S. Treasury.
This guarantee is egregiously provided to Fannie and Freddie for free. Neither has ever paid even one cent for it. It is part of the government’s attempt to promote housing, not to mention helping out the important political constituencies of the housing and housing finance industries that benefit from it. Fannie and Freddie could not exist for even a day without this huge and extremely valuable government guarantee, which, because it is free, acts as a giant subsidy.
Fannie and Freddie used frequently to claim that this institutional design, with them at the center of a taxpayer-guaranteed housing finance system, was “the envy of the world.” It wasn’t, but it did make and still makes the U.S. unique in global housing finance.
With the collapse of the great housing bubble which greeted the opening of the 21st century, Fannie and Freddie went broke and were recapitalized by the U.S. Treasury in a $190 billion bailout, making good the government’s guarantee and making whole every creditor. The government also took over complete control of the management of Fannie and Freddie. They are thus no longer privately owned and managed companies and can no longer properly be called, as they used to be, “government-sponsored enterprises.” Instead, they have become overwhelmingly government-owned and entirely government-controlled companies—simply part of the U.S. government.
The Treasury’s equity stake in Fannie and Freddie is now $367 billion. This is the liquidation preference of their combined senior preferred stock. Subtracting this government stake from the total equity of $179 billion leaves Fannie and Freddie with a private equity of negative $188 billion. On top of owning the bulk of the equity through its senior preferred stock, the Treasury has the right to acquire 79.9% of Fannie and Freddie’s common stock almost for free—the exercise price of the option it holds is one-thousandth of a cent per share. Hard to get closer to zero than that.
The Director of the Federal Housing Finance Agency, in his legal role as Conservator, has had total governance power over Fannie and Freddie since 2008. Under the law, the Conservator wields the power of the boards of directors and the executives, as well as being the regulator. He has moreover made himself Chairman of both of the boards. As Director of the FHFA, he is responsible to and removable by the President of the United States. A pointed recent example of Fannie and Freddie’s current governance was the instruction from the President for them to buy for their portfolio $200 billion of mortgage-backed securities. The FHFA Director announced that Fannie and Freddie would execute the order and they obeyed.
Fannie and Freddie’s primary ownership by the government and total governance by the government has so far lasted nearly 18 years. It has outlasted numerous attempts at legislative reform and many proposals for what has been called “privatization” but never really was, because all these proposals include maintaining the free government guarantee. In our opinion there is no credible escape from the current situation and it is likely to continue indefinitely.
As part of the government, Fannie and Freddie have become even bigger than they were before. With combined assets of $7.8 trillion and $7.6 trillion in liabilities, they are an essential part of the finances of the U.S. government. That the Treasury guarantees those trillions in liabilities means that they are in reality part of the government’s debt. Accurately reporting this $7.6 trillion as government debt, which it really is, would increase the reported U.S. government debt held by the public by about 25%—from $30.8 trillion to $38.4 trillion as of December 31, 2025. The even larger category of total U.S. government debt would increase to the pretty astonishing amount of $46.1 trillion.
Naturally there is a strong desire of politicians and Treasury managers to keep Fannie and Freddie’s debt off the government’s books. Nonetheless, that is where it belongs. We are not betting on its being properly reported there any time soon, however.
Fannie and Freddie operate at extremely high, non-market, government-guaranteed leverage. Their leverage and most of their profit is made possible by their free guarantee from the Treasury.
An essential question to understand Fannie and Freddie’s true nature is: What would happen to Fannie and Freddie if they had to pay a fair price for their guarantee? Of course, that includes the question: What would a fair price be?
There are two components to the guarantee fee Fannie and Freddie should pay the Treasury. First is the Risk Fee for the risk that Fannie and Freddie impose on the Treasury of future losses and future bailouts. The second is the Cost Offset Fee to make up for the increase in the cost of the Treasury’s own debt that Fannie and Freddie cause.
We estimate the Risk Fee by the close analogy to what the largest, “Too Big to Fail” banks pay the Federal Deposit Insurance Corporation for the implicit guarantee of all of their liabilities which they too receive from the government. We believe the Risk Fee should be about 12 basis points (0.12%) of Fannie and Freddie’s total liabilities per year. For the combined $7.6 trillion in liabilities, this fee would be $9.1 billion per year. To pay that would take about 36% of Fannie and Freddie’s combined 2025 pretax profit.
Further study may determine that the fair Risk Fee is higher or lower. In any case, it is absolutely certain that the right fee is not zero, which it has always been up to now.
The Cost Offset Fee reflects the fact that the constant presence of trillions of dollars of Fannie and Freddie mortgage-backed securities and debt compete with the Treasury’s own debt for the purchases of conservative global investors. Using and updating the Federal Reserve’s analysis of the relationship of the effects of Fannie and Freddie’s MBS on the cost of U.S. Treasury debt, the AEI Housing Center estimated the fair level of the Cost Offset Fee to be from 38 to 57 basis points (0.38% to 0.57%) per year on Fannie and Freddie’s liabilities, or a mid-point of 48 basis points (0.48%). This would just reimburse the Treasury for the added interest cost that Fannie and Freddie impose on it.
Adding together the two components of the appropriate guarantee fee gives an estimated total fee of 60 basis points (0.60%). To give Fannie and Freddie the benefit of the doubt, we cut this in half, to 30 basis points (0.30%).
What is the resulting effect of Fannie and Freddie? To pay the 30 basis point guarantee fee would require $22.8 billion, which is about 90% of their combined 2025 pretax profits. Others may of course have differing estimates of the right fee for Fannie and Freddie to pay the Treasury for the guarantee which makes their existence possible, but any legitimate fee would constitute a very significant portion of their pretax profits.
This result speaks to an essential truth: the essence of Fannie and Freddie is to convert a free government guarantee into their profit. If it is ever contemplated to move them out of the government and again into private ownership and management, this absolutely has to be fixed, which means adopting a fair guarantee fee they have to pay the U.S. Treasury. But such a fee makes it impossible for the potential private investors to want to invest.
The alternative, which we expect to continue, is for Fannie and Freddie to go along indefinitely under government ownership and government control, the 20th century idea of “government-sponsored enterprises” having failed.
July 3: Sympathy for Thomas Jefferson Day
Everybody knows about July 4, but what was happening on July 3, 1776? On that day, the draft of the Declaration of Independence submitted by Thomas Jefferson was edited by the Continental Congress, meeting as a committee. Jefferson had to sit there, “the writhing author,” says my well-worn history of the Declaration [1], while his words were criticized, deleted and altered. Jefferson “was far less happy when his handiwork was subjected to what he called the ‘depredations’ of Congress.” He “kept silent for propriety’s sake,” but “in his opinion, they did a good deal of damage [as] the delegates took a hand in the drafting.”
All those who have worked assiduously on their writing, then had it edited by a committee, will have lively sympathy for Jefferson every July 3!
The Congress “effected economy in words,” “deleted unnecessary phrases,” “eliminated the most extravagantly worded of all the charges [against King George],” “deleted a passage in which Scottish mercenaries were coupled with foreign [ones],” changed Jefferson’s final paragraph so as to include in it the precise language of the resolution of independence just adopted [on July 2]”, and “left out several moving phrases of his toward the end.”
I have reviewed the edits made by the Congress, and find that they definitely improved the final, world historical document. Nonetheless, to sit there while your work suffers “depredations” by a committee of your colleagues, even if they are in fact improvements, is surely difficult. Our sympathy for the author should be undiminished.
July 3, 2023
[1] Dumas Malone, The Story of the Declaration of Independence, Oxford University Press, 1954.
The Crisis at the Fed That No One Talks About
It’s staring the new chairman of the central bank squarely in the face.
Published in The New York Sun.
Of all the issues facing the Federal Reserve’s new chairman, Kevin Warsh, one that gets little public attention is the financial condition of the Fed itself. In addition to its much-publicized roles of setting short-term interest rates, which may be headed back up, and creating inflation, which is already too high, the Fed is a giant financial enterprise. It has total assets of $6.9 trillion as of March 31 combined with negative real capital.
The Fed has lost hundreds of billions of dollars due to its huge interest rate risk position. This costly risk was established under the then-chairman, Ben Bernanke, who assured Congress it would be temporary. It wasn’t. It was continued under the regimes of Janet Yellen and Jerome Powell and remains embedded in the Fed’s balance sheet today, almost 18 years after Mr. Bernanke’s original gamble.
It’s waiting for Chairman Warsh. The interest rate risk position is fundamentally simple. It consists of making long-term, fixed rate investments financed by floating rate funding: invest long, borrow short. It closely resembles the risk of a typical 1980s savings and loan. Because it took this risk, the Fed reported large net losses for the three calendar years 2023, 2024, and 2025, with the losses totaling the egregious sum of $211 billion.
This is more than four times the Fed’s total book capital of $46 billion, which means that its capital is gone, even though the Fed refuses to show any reduction in the capital on its financial statements. The Fed argues that it can on its own decide on a special accounting treatment for itself, different from everybody else, which it would never allow its regulated banks to follow.
In addition to the annual operating losses, the Fed has suffered as of March 31 mark-to-market losses of $857 billion. The Treasury securities the Fed owns are worth on the market $546 billion less than it paid for them. Its mortgage-backed securities are worth $311 billion less than it paid. The operating losses and mark-to-market losses together add up to more than $1 trillion and are 23 times the Fed’s reported book capital.
The Fed has often claimed that no one should worry about its enormous losses, because it wasn’t set up to be a “profit maximizer.” However, the Fed most certainly was set up to make profits for the government. It forks over almost all its profits, which it always has had historically, to the Treasury. When it makes losses instead, payments don’t go to the Treasury, so the federal deficit and the national debt grow correspondingly bigger. The Fed’s losses are the Treasury’s and taxpayers’ losses.
The owners of the Fed’s stock should also care about its losses. All $39.7 billion of the Fed’s paid-in capital is owned by private banks. Under a little-known provision of the Federal Reserve Act, they are liable to be assessed up to twice their investment in the stock to offset losses. This is disclosed in the Fed’s financial statements, although pretty well buried down in the footnotes.
The Fed could reduce its interest rate risk by selling some of its long-term Treasury securities and mortgage-backed securities. If it did, though, the mark-to-market losses would become permanent cash losses. The Fed could no longer claim they were only “paper losses.” On top of that, serious Fed selling would push long-term Treasury and mortgage interest rates higher: Not a political winner.
In the first quarter of 2026, the Fed reported a modest profit of $1.4 billion. Does this mean its profitability and interest rate risk problems are over? It doesn’t. My estimate is that the Fed has — on a net basis — about $2.5 trillion in long-term assets funded short. The bond market is now expecting short-term interest rates to rise again this year. If they do, it would cost the Fed $25 billion or so per year for a 1 percent rise in rates.
Moreover, the profit the Fed reported for the first quarter was only possible because the Fed is being heavily subsidized by the Treasury. To do this, the Treasury holds huge interest-free deposits at the Fed — $893 billion of them on March 31. At current interest rates, these give the Fed an additional profit of $33 billion per year, while increasing the Treasury’s deficit for the year and increasing the national debt by the same $33 billion.
Why doesn’t the Fed pay the Treasury, and thus the taxpayers, the same interest rate on deposits that it pays the private banks? Obviously, it should, and Congress needs to fix this. When we subtract the Treasury’s generous subsidy, the central bank is still running a significant loss, which will grow larger if short-term interest rates rise again.
A New Head for the Fed
Here's what new Fed Chairman Kevin Warsh might be thinking about right now.
Published in Law & Liberty.
Being chairman of the Federal Reserve Board, which includes being its chief executive, is one of the very top jobs not only in the country, but in the world. In the US, the Fed is the central bank, money printer, inflation-creator, and emergency lender to the world’s most important economy and financial markets; it is also all of those to the global dollar-denominated system of payments, borrowing and investing. Its new chairman, Kevin Warsh, is highly intelligent and knowledgeable in finance, economics, and politics. He is also very thoughtful. Here are five of the issues he is or might be thinking about.
1. Shrinking the Fed: Chairman Warsh has been clear about his interest in shrinking the bloated balance sheet of the Fed, and in reducing its heavy interventions or so-called “footprint” in financial markets. In the first quarter of this year, the Fed grew by $35 billion, bringing its total assets to $6.9 trillion as of March 31, 2026. That is 7.5 times as big as the Fed was at the end of 2007, when it produced its last historically normal balance sheet. Ever since then it has been in the Ben Bernanke-induced, abnormally inflated balance sheet mode, which Warsh has often rightly criticized. Although Bernanke, when he was Fed Chairman, promised Congress that this would be temporary, it has not been, but has lasted more than 17 years, so far. Can the Fed shrink back to normal?
At the end of 2007, the Fed’s total assets were $894 billion. That was 6.2 percent of nominal GDP and 8.3 percent of commercial banking assets. To get to these same percentages today, the Fed would have to shrink by more than $4 trillion, including selling a couple trillion of long-term Treasury securities. In 2007, the Fed’s investment in mortgage-backed securities was zero, which is what it should be. How the Fed convinced itself to become and remain the biggest investor with the biggest footprint in mortgages is a puzzle indeed. To get back to zero, it would have to unload its $2 trillion in MBS, the purchase of which so distorted the mortgage market and house prices.
Chairman Warsh has of course considered how any material sales of investments to shrink the Fed would make the prices in the Treasury bond and MBS markets go down and their interest rates go up. Should the Fed push bond and mortgage interest rates up, increase the Treasury’s interest cost, and make houses even less affordable? That seems to have no chance of being a political winner.
On top of that, the Fed has a mark to market loss of $546 billion on its Treasury investments and a loss of $311 billion on its MBS. To sell them would be to move such losses from unrealized, “paper” losses, to realized, cash losses, which would have to be reported on its profit and loss statement. The Fed’s total mark to market loss of $857 billion is about 18 times its total book capital of $48 billion. The Fed insists that nobody cares about its losses, but such numbers would be truly enormous, embarrassing, and obviously poor PR.
Shrinking the Fed looks desirable, but is apparently a longer-term, not a short-term, project. Since the Fed’s most important function is to finance the government of which it is a part, I have suggested that a reasonable longer-term target size for the Fed might be 10 percent of the national debt. Today, that would mean a Fed about $3 trillion smaller than it is.
2. The Unknowable Right Interest Rate: Eight times a year we are treated to the melodrama of the Fed’s Open Market Committee meeting to set, and since the Bernanke time, to forecast with their “dot plots” interest rate paths. Upon reflection, it should be clear to everybody that no committee, including this one, can actually know what the right interest rate is, and certainly it cannot know what future interest rates will be. The committee’s forecasting record makes that apparent. As then-Fed Chairman Jerome Powell so rightly observed, “We are navigating by the stars under cloudy skies.” I think this saying should be forever enshrined in Fed lore right next to William McChesney Martin’s famous “punchbowl” line.
Chairman Warsh seems inclined to get rid of the “dot plot” forecasting and any inclination for the committee members to feel committed by their past recorded guesses. This is a good idea. In addition, will he privately brood about the larger question of whether it really makes sense to have a national price fixing committee for interest rates?
3. Perpetual Inflation at 2 percent?: Among the Fed’s heirlooms from the Bernanke years is the notion that the Fed can on its own, without Congressional approval, commit the United States to perpetual inflation at the rate of 2 percent per year—in other words, to quintupling prices in an average lifetime. The inflation targeting regime has given us the historically anomalous experience of central bankers claiming they have to get inflation up. This regime has presided over not only the runaway inflation of 2021–22, but also current inflation at nearly twice the target rate.
It is now 14 years since the Fed unilaterally announced its target of 2 percent inflation forever. It seems like time for a critical reconsideration of it. International financial expert William White has a forthcoming article: “The Inflation Targeting Framework for Monetary Policy Needs to be Challenged.” This seems right to me. Chairman Warsh’s comments on how to think about inflation suggest he may be open to such a reexamination.
4. The Role of the Money Supply: Did the Fed and other central banks somehow forget about the perennial role of creating too much money in fostering inflation and depreciating the currency? It seems that by rejecting a mechanical relationship of money supply and prices, they embarrassingly made the opposite error, which explains their woefully wrong forecasts of inflation and interest rates in the early 2020s.
The British economist Tim Congdon, whose forecasts in this period were based on money supply and were far superior to those of the Fed and the Bank of England, concludes that “the behavior of money growth must be restored to a central position in policy-oriented macroeconomic analysis.” Chairman Warsh might be thinking about whether the Fed should take this advice.
5. Thinking Clearly About the Fed’s Finances: Among other things, the Fed is a giant financial enterprise. It is designed to make money for the government, but in recent years has lost heavily instead, with combined reported net losses for the three years 2023–25 of $211 billion. To this should be added the $857 billion in mark to market losses discussed above.
The Fed reported a net profit of $1.4 billion in the first quarter of 2026, but this modest profit was only possible because the Fed is being heavily subsidized by the US Treasury. The Treasury does this by holding vast interest-free deposits in the Fed—of $893 billion on March 31 of this year. At current interest rates, these will give the Fed $33 billion in profit, which it will not return in remittances to the Treasury this year, only in the hazy future. This increases the current year’s federal deficit and runs up the national debt by the same $33 billion—not a very good deal for the Treasury or the taxpayers. To fix it, the Fed should simply pay the Treasury interest on its deposits, the same way it pays interest to banks.
For clarity, you can divide the Fed into three main functions: issuing currency, which at current interest rates makes profits of about $87 billion a year; the $33 billion in profit from the Treasury subsidy; and then everything else, which includes the Fed’s trillions in underwater long-term investments. This third function appears to be making losses at the rate of about $113 billion a year.
As chief executive of the Federal Reserve and a financial expert himself, Chairman Warsh might be thinking of how to provide rigorous explanations to Congress of the Fed’s financial performance, balance sheet and financial outlook, making these clear to the legislature, which is his boss.
Lives Entwined in the Great Stock Market Collapse
Published in Civitas Outlook.
Ross Sorkin's 1929 is not a book about macroeconomics, the causes of economic cycles, or theories of financial market behavior. It is a book about people.
In the Afterword to 1929, Andrew Ross Sorkin reflects that in this book, he wanted “to restore the texture and detail of the human lives at the center of an epic historical event. Who exactly were the people caught up in it, what did their lives look and feel like?” In this, Sorkin has fully succeeded. He has created a most readable account of the personalities, careers, opinions, decisions, actions, hopes, fears, risk-taking, and sometimes descent from hero to bum of those entwined in the intoxicating boom and crushing bust of the 1920s stock market. We can’t help being interested in the characters he deftly portrays.
This book is not about macroeconomics, the causes of economic cycles, theories of financial market behavior, or the author’s proposals for institutional redesign or grand reforms. There are no mathematical formulas or graphs, and no statistics, other than reporting the heady rise and headlong drop in stock prices of the time, and, in later sections, the staggering numbers of bank failures. It is a book about people.
In Sorkin’s drama, they appear in five acts:
-Life and personalities at the top of the great 1920s stock market bubble
-The Crash of October 1929
-The deepening Depression, leading to the banking panic of 1933
-Hoover exits; Roosevelt creates a heroic role for himself
-Aftermath: 1930s Congressional investigations, reform legislation, and criminal indictments; the later life of the characters.
A problem with writing this kind of history is that readers already know, in general, what happened. This can impart to the drama a retrospective inevitability that did not exist for the people at the time. Instead, they found themselves in a confusing present with an unknowable future, just as we do. Sorkin relates colorful examples of conflicting predictions of the time.
John Jabob Raskob, “one of the wealthiest men in the nation,” chairman of the Democratic National Committee, and an important character in the book, assured the public in 1929 that “with just $15 per month, ‘wisely invested,’ anyone could become wealthy through the stock market within twenty years.” Said the Literary Digest, “‘This is the greatest vision of Wall Street’s greatest mind.”
About the same time, Thomas Lamont, the second most senior partner in J.P. Morgan and Co. and a principal actor in the book, was in Europe, negotiating the restructuring of the German reparations from World War I. From there, he wrote his son, “Prices can go lower, so be sure to keep plenty of cash…I keep feeling cash is a good asset.”
The stock market reached its peak in September 1929, with the Dow Jones Industrial Average at 381. Of course, they didn’t know then it was the peak. “The market had experienced nearly seven years of uninterrupted growth,” as Sorkin observes. Had you been living then, do you think you would have been buying or selling at that point?
In that month, the brilliant and famous economist, Irving Fisher of Yale University, opined, “Stock prices are not too high and Wall Street will not experience anything in the nature of a crash.” He said, this reflected, among other factors, “inventions such as the world has never before witnessed.” (This may sound familiar.) In October, he further memorably pronounced: “Stock prices have reached what looks like a permanently high plateau.”
A sense of the times comes with another of Fisher’s arguments: The market had not yet “reflected the beneficent effects of Prohibition, which had made American workers more productive and dependable.”
On the opposite side, economist Roger Babson issued a famous forecast: “Sooner or later a crash is coming and it may be terrific. Wise are those investors who now get out of debt… The stock market boom will collapse like the Florida [land] boom.” (This is the only mention in the book of that other 1920s bubble.) Babson continued, “Sellers will exceed buyers…paper profits will begin to disappear…margin accounts will be closed out…there may be a stampede for selling which may exceed anything that the stock exchange has ever witnessed.” (Sorkin does not mention that Babson was also the Prohibition Party’s 1940 candidate for U.S. President.)
Charles Merrill, the co-founder of Merrill Lynch, gets only a bit part, but it includes his early call, which looks very good in retrospect: Merrill “had been telling his clients to get out of the market since March 1928.” But between the end of March 1928 and early September 1929, the market rose 80 percent.
So would you have listened to Merrill, or to Charles Mitchell, the Chairman of the National City Bank of New York (now Citibank), a leading banker of the day? Boarding an ocean liner for a four-week vacation in September 1929, Mitchell told the press, “There is nothing to worry about in the financial situation of the United States,” and upon his return in October, “Although in some cases speculation has gone too far…the markets generally now are in a healthy condition.” Mitchell is a prominent character in the book, starting the story at the top of Wall Street, falling hard and ignominiously in the 1930s, and rising again.
Herbert Hoover, a very intelligent and capable man, had become President of the United States in March 1929. He had long been convinced that the stock market suffered from excess speculation. Now, six months into the job, “rattled by the roller-coaster stock market and [the] conflicting comments from Babson, Fisher and Mitchell, the president dispatched an envoy [to] Lamont. … Should his administration do something to stop speculation before it was too late?” Lamont’s advice was that “Corrective action on the part of public authorities…need not at this time be contemplated.”
The Crash came. On Black Thursday, October 24, Babson’s scenario became reality with “a blizzard of sell orders…brokers liquidating the accounts of customers who couldn’t meet their margin calls… soon many stocks had no bids at all…everybody wants to sell out.”
This set the stage for the dramatic private intervention of the leaders of Wall Street. Sorkin tells the story very well. “Lamont remembered the Panic of 1907 and tried to think: What would J. Pierpont Morgan do?” The answer was for the leading firms to create a pool to buy stocks amid selling and stop the panic.
Richard Whitney, the Vice President of the New York Stock Exchange, was their broker. “At 1:30 p.m. the tall, supercilious Whitney strode unto the trading floor with a smile…to post 2 where in a loud, booming voice, he asked what the last bid for U.S. Steel had been. ‘One ninety-five,’ the specialist said ‘Ten thousand at two-oh-five,’ Whitney announced. … For a split second there was silence … Then a shout of elation went up and spread across the room.” Whitney proceeded across the floor, “loudly buying shares.” Would the plan work? It looked like it would. “The rout was halted. … Whitney was hailed as a hero [and dubbed] “Wall Street’s White Knight.”
But five days later, on Black Tuesday, October 29, it all came apart again, with renewed floods of selling and prices collapsing By the end of the day, the Dow Jones index had fallen to 230, or down 40 percent from its September peak The Wall Street elite’s best shot had failed Subsequently, despite various interim rallies and optimism, stock prices would fall for the next three years, ultimately going down by 89 percent from the peak.
Many interesting characters appear on Sorkin’s stage. Among them is Winston Churchill, out of political office, touring America to build an audience for his writing, who took time out to make heavy losses in the stock market.
There is Jesse Livermore, famous in his day as a big-time financial speculator, whose life was fictionalized in the popular 1923 novel Reminiscences of a Stock Operator. In October 1929, Livermore made huge profits by being short the market; his gains, Sorkin tells us, amounted to $100 million. Later, he lost it all and finally committed suicide, writing to his wife, “I am a failure.”
In the Washington D.C. scenes, Senator Carter Glass often appears, a Jeffersonian Democrat, great critic of Wall Street and of Charles Mitchell in particular, and co-sponsor of the landmark Glass-Steagall Act of 1933. About Black Tuesday, he said with schadenfreude, “It is just the result of Mitchellism … It is a sign the gamblers have reached their limit.”
As Sorkin takes the story into the 1930s, the Depression involves thousands of bank failures, literally. Hoover, having lost the 1932 election by a landslide, faced a nationwide bank panic during this lame duck period. He tried to get the newly elected Franklin Roosevelt to work with him on a national bank holiday, but Roosevelt refused.
With the country in the midst of a banking crisis, Hoover was outplayed by the master politician, manipulator, and rhetorician, Roosevelt, who then could take center stage as the hero with his own national bank holiday, using much of the material already worked out by the Hoover administration, and launching the New Deal, which dominated the rest of the 1930s. Near the end of that new drama, we may note, with Roosevelt’s policies, the 1939 unemployment rate was still 17 percent—but that is a different book.
1929 does not take up and is not interested in how the stock market finances productive investment, entrepreneurial ventures, and economic growth, and produces long-term profits. It focuses rather on how it can generate excesses, like the huge 1920s bubble and bust. Sorkin muses on the last page that overall “People will find new ways to believe the good times can last forever … humanity will again and again lose its head.” However, fundamental uncertainty means we can’t have one part of this fascinating combination without the other, and it is highly unlikely that we in the present are any smarter than the characters caught in the great drama of a century ago.
Seven Questions for Kevin Warsh, Newly Confirmed as Chairman of the Fed
And some startling answers from the Sun’s monetary columnist.
Published in The New York Sun.
The Federal Reserve is at the center of the pure paper money system of the United States and the world. As the Fed transitions to a new chairman, it is timely to consider some questions about this remarkable, powerful, dangerous, and allegedly “independent” institution. Here are seven questions for the new chairman, Kevin Warsh, and his colleagues:
Do we need a national price fixing committee for interest rates?
Answer: No.
Nothing is more obvious in free market economics than that having centralized price fixing by the government is a really bad idea. The constant discovery of clearing prices by competitive markets is what is needed. Yet the Fed’s Open Market Committee is a national price fixing committee by another name for one of the most important prices: interest rates. Amazing mistake, if you think about it.
Does the Fed know what it’s doing?
Answer: No.
As the outgoing chairman of the Fed, Jerome Powell wittily and correctly said about the Fed, “We are navigating by the stars under cloudy skies.” So it is, and so it must be. Neither the Fed nor anybody else ever knew or ever can know what the correct interest rates are. To do that they would have to know the future, and the economic future is always uncertain, not only unknown but unknowable. The Fed’s forecasting record is poor because it cannot know what it is really doing.
How much money has the Fed lost on its “QE” gamble — and whose money was it?
Answer: It has lost more than $1.3 trillion of the taxpayers’ money.
The Fed made a gamble on what it called “Quantitative Easing,” or “QE,” described by its chairman at the time, Ben Bernanke, as a “shot in the dark.” It was a macroeconomic gamble that stoked asset price inflations. It was a financial gamble with the Fed’s own earnings and capital.
The huge resulting total losses are the sum of three factors. The Fed reported net operating losses of about $220 billion since 2022. In addition, the QE losses wiped out more than $300 billion in profits the Fed made by issuing currency and holding interest-free deposits from the Treasury.
So quantitative easing’s operating losses exceed $500 billion. On top of that, QE has resulted in mark-to-market losses of $844 billion. In sum, the more than $1.3 trillion in losses mean that the costs will be borne by the taxpayers and suggest that the Fed has lost the entire $47 billion capital of its commercial bank shareholders about 27 times over.
Does the Federal Reserve Act assign the Fed a goal of “price stability”?
Answer: No.
“Price stability” is a tricky term that means, according to the Fed, perpetual inflation at some rate it chooses. It means that overall prices always rise. That is not what the Federal Reserve Act says. The Act assigns to the Fed an objective of “stable prices,” a clear term. It means prices that are stable. In other words, it means average inflation of approximately zero. The Fed was rhetorically clever to use “price stability” in all its presentations when it decided to pursue perpetual inflation, since it obviously was not pursuing stable prices.
Should the Fed have a monopoly in American money?
Answer: No.
As suggested by Friedrich Hayek in “Competition in Currency,” an essay now canonical among cryptocurrency enthusiasts, to control a central bank’s urge to impose inflation on the people, one could create competition in currency. Then the people could use the money they believe will best hold its value. The same essay shows that what Hayek really wanted was a renewed monetary role for gold to evolve from this competition.
Could there be a renewed monetary role for gold?
Answer: We should try to develop one.
The Fed might start by owning some gold to diversify its assets. Today, unlike most major central banks, it owns exactly zero gold and so has missed out on the great gold rally, which was really the great depreciation of the Federal Reserve dollar — by 99 percent against gold since 1971. Various American states have projects to make gold a legal tender, which might allow 100 percent gold-backed electronic currencies to compete with paper dollars.
Should the Federal Reserve be “independent”?
Answer: No.
No part of the government in any branch should be an independent fiefdom. Fundamental to our constitutional republic is that every part of the government must be a part of our system of checks and balances. In the Fed’s case, this means there needs to be much enhanced accountability to the Congress.
Fannie, Freddie, and the National Debt
Published with Edward J. Pinto in Law & Liberty.
Fannie and Freddie are part of the government and need to be included in its consolidated financial statements.
Fannie Mae and Freddie Mac are huge, with $7.8 trillion in assets and $7.6 trillion in liabilities. They are an essential part of the finances of the US government. But we do not find them as part of the government’s consolidated financial statements. We should.
This is due not only to their sheer size but also because of the giant taxpayer risk they represent, the government’s principal ownership of them, the total government control of their operations, and the obvious fact that these conditions are not temporary but long-term and ongoing. We believe that without consolidating Fannie and Freddie, a true and fair view of the government’s financial condition is not possible.
We understand the natural desire of politicians to keep Fannie and Freddie’s $7.6 trillion in liabilities off the government’s consolidated books. Accurately recording these obligations would increase the reported amount of government debt held by the public by about 25 percent—from $30.8 trillion to $38.4 trillion as of December 31, 2025. With Fannie and Freddie correctly consolidated, the total government debt would be $46.1 trillion.
Obviously, it is politically tempting to keep the obligations Fannie and Freddie impose on the taxpayers pushed obscurely down into the footnotes. Indeed, to get Fannie’s debt off the government’s books was the very reason for making it a so-called “government-sponsored enterprise” in 1968, a status later repeated for Freddie. We suggest that this twentieth-century idea has become obsolete.
Fannie and Freddie’s nature has changed radically in this century. When we apply the current facts about them to the governing accounting principles of the Federal Accounting Standards Advisory Board (FASAB), it appears the 2008 decision not to consolidate them is no longer defensible. To summarize today’s reality, Fannie and Freddie are no longer government-sponsored, privately-owned, and managed enterprises. Instead, they are government-owned and government-controlled agencies. Nothing is clearer than that the taxpayers are on the hook for all their debt and risk, and that government officers are fully in command. They are just parts of the government now and should be accounted for accordingly.
The governing “Statement of Federal Financial Accounting Standards No. 47, Reporting Entity,” defines the criteria to decide between a “consolidation entity” included in the government’s consolidated financial statements, and a “disclosure entity” which resides in the footnotes, off-balance sheet. These criteria are whether “as a whole, the organization: a) is financed through taxes and other non-exchange revenues; b) is governed by the Congress or the President; c) imposes or may impose risks and rewards to the government; and d) provides goods and services on a non-market basis.” Note 1 to the US Government Financial Statements adds the view that Fannie and Freddie’s “relationship to the government is not expected to be permanent.”
Taking these in order:
Fannie and Freddie’s financing completely depends on the government.
All of Fannie and Freddie’s revenues and financing depend upon the guarantee of their obligations by the government. Without this guarantee, neither of them could exist for a day. This guarantee means their revenue depends on access to the taxing power of the government. Moreover, the guarantee is provided to them for free, the essence of a non-exchange arrangement. This is a permanent arrangement.
There is no non-government governance of Fannie and Freddie and has not been for more than 17 years.
It is often said that this guarantee is “implicit,” but no informed person doubts that it is real. And everybody is right about this. President Trump, for example, has confirmed the government guarantee of Fannie and Freddie and stated that it will be retained. We feel sure that the reality of this guarantee, essential to Fannie and Freddie’s very existence, is a view shared by the US Treasury, by all Fannie and Freddie’s customers and creditors, and by FASAB, too.
Fannie and Freddie’s equity financing also depends on the government. The government’s stake in their equity is a $367 billion liquidation preference in their combined senior preferred stock. Subtracting this government stake from their total equity of $179 billion would leave them both technically insolvent, with a combined non-government equity of negative $188 billion. On top of this, the government has the right to acquire 79.9 percent of the common stock of both for one-thousandth of a cent per share. This totals to less than $55,000.
Fannie and Freddie are completely controlled by the government.
Fannie and Freddie are entirely subject to their conservator, who is the director of the Federal Housing Finance Board. Under the law, the conservator wields the complete power of their boards of directors and executives as well as being their regulator, and moreover, he has made himself the chairman of both of their subordinate boards. The director of the FHFB is removable by and responsible to the president of the United States. An excellent recent example of Fannie and Freddie’s governance is their instructions from the government to buy $200 billion in mortgage-backed securities. As reported by National Mortgage Professional, “In early January, President Donald Trump said he is ordering his ‘representatives’ [Fannie and Freddie] to buy $200 billion in mortgage bonds to bring down housing costs … FHFA Director Bill Pulte said on X that Fannie and Freddie will execute the purchase.”
There is no non-government governance of Fannie and Freddie, and has not been for more than 17 years.
Fannie and Freddie impose large risks on and offer rewards to the government.
Because it guarantees their $7.6 trillion in obligations, the government remains fully at risk for big losses at Fannie and Freddie, which may occur, just as it did when Fannie and Freddie went broke from bad loans in 2008. The Treasury provided them a $190 billion bailout, buying senior preferred equity that it still owns. Conversely, when Fannie and Freddie have been profitable under current arrangements, the government has benefited by dividends it has received, or by increases in the liquidation preference of its senior preferred shares, in effect, a dividend in kind. Any increase in the value of the Treasury’s option to acquire most of Fannie and Freddie’s common stock for less than $55,000 would also be a reward.
Fannie and Freddie provide financial services on a non-market basis.
Fannie and Freddie operate at extremely high, non-market leverage. Most of their earnings are made possible by their non-market, free guarantee from the government, for which, by the way, neither has ever paid even one cent. We have calculated that if they had to pay a fair rate for their $7.6 trillion of free government guarantee, it would absorb 50 percent to 100 percent of their pre-tax profit. The entire political rationale for Fannie and Freddie’s existence is that they create mortgage financing at interest rates below what the market would offer, possible only because of their deep links to the government, of which they have now become simply a part.
The characteristics that make Fannie and Freddie “consolidation entities” are not temporary, but are long-term or permanent. Having the government guaranty, being financially dependent on the government, imposing large risks on the government, and operating on a non-market basis are all permanent parts of Fannie and Freddie. Being mostly owned by and completely controlled by the government is not temporary, since it has been going on for 17 years, and the situation has outlasted many attempts at legislative reforms or attempted so-called “privatizations.” There appears to be a strong probability that the current situation will simply continue. President Trump has said as much: “I will stay strong in my position on overseeing them as President.”
Considering all these elements as a whole, we conclude that Fannie and Freddie should be consolidated in the US government’s financial statements. As a result, the proper consolidated total of government debt is $7.6 trillion greater than officially reported.
Letter: Here are three things the Fed is actually good at
Published in the Financial Times.
Your Big Read feature “Is Warsh set to be the next Fed fall guy?” (April 20) repeats a myth which should be long dead: that the Federal Reserve’s job includes “the management of the biggest economy on the planet”.
On the contrary. To “manage the economy” would require knowledge of the future that neither the Fed nor anyone else has, or can have.
At its creation in 1913, it was thought that the Fed would prevent future financial crises and panics. Obviously it didn’t.
In the heyday of Keynesian hopes in the 1960s, it was thought that the Fed could be part of ending financial cycles. Obviously it couldn’t.
As Fed chairman Jerome Powell brilliantly observed in August 2023, the Fed is “navigating by the stars under cloudy skies”. So it is and always must be.
The Fed actually is good at three things. One, printing money to finance financial crises. Two, creating constant inflation and depreciation of the currency it creates, and three, supporting the power of the government by monetising the government’s debt.
But “managing the economy” is far and forever beyond its capability.
How Much Should the Federal Reserve Shrink?
Whether our central bank should or could shrink, and if so, how much, has become a topic of public debate.
Published in The New York Sun.
Robert Higgs, in his book “Crisis and Leviathan,” shows how the size, power, and intrusiveness of the government feed on crises. With each crisis, the government becomes bigger. After the crisis is over, it may shrink some, but it rarely goes back to its former size.
The bloated balance sheet of the Federal Reserve is a perfect demonstration of this phenomenon. At the end of 2007, before the panic of 2008, the Fed produced its last historically normal annual balance sheet. It had total assets of $894 billion. It owned zero mortgage securities.
During the ensuing years, the Fed vastly expanded its balance sheet to a size that was previously unimaginable. By Peak Fed in March 2022, it had total assets of $8.9 trillion, or 10 times its 2007 level. It had investments in mortgage securities of $2.7 trillion, three times its total 2007 assets.
Since then, just as Mr. Higgs would predict, the Fed’s size has been reduced, but to nowhere near its previous level. As of the end of March 2026, the Fed’s total assets are still $6.7 trillion or 7.5 times their 2007 level and it still owns $2 trillion in mortgage securities, compared to the zero it should have. The Fed has stopped reducing its size — it is now $34 billion bigger than it was at the end of 2025.
Whatever happened to the assurance Chairman Bernanke’s gave in 2011 to Congress that “there will be no permanent increase… in the Fed’s balance sheet”? We can consider it either a memorable broken promise or a fully flubbed forecast.
The Fed has two basic parts: the mundane job of simply buying Treasury securities with the United States currency it has the monopoly on issuing; and everything else. In 2007, the mundane “Currency Fed” had $792 billion in currency outstanding, so everything else in the Fed’s balance sheet totaled only $102 billion.
At Peak Fed, the “Everything Else” part of the Fed, which had come to include in effect a giant savings and loan for holding mortgage assets and an even bigger hedge fund for investing in long-term Treasury securities financed overnight, totaled $6.7 trillion. In other words, the activist, interventionist, financial risk-taking part of the Fed had increased since 2007 by 66 times. As of today, that increase is still 42 times.
The financial results of the Fed’s risk taking are an aggregate operating loss of $224 billion plus a mark-to-market loss of $845 billion, or well over $1 trillion in total. These are costs not just to the Fed itself but to the Treasury and the taxpayers. In addition, the Fed’s mortgage buying spree, by driving mortgage interest rates to abnormally low levels, pushed house prices up to abnormally high levels.
The “affordability crisis” in American housing thus significantly reflects the results of the Fed’s bloated balance sheet. Even though the Fed should get out of its mortgage investments, it certainly does not want to sell them now because doing so would create a more than $300 billion realized loss. On top of that, selling would drive mortgage interest rates up — a politically unacceptable result.
Whether the Fed should or could shrink, and if so, how much, has become a topic of public debate. How much shrinkage would it take to get the current Fed back to the 2007 base case, appropriately adjusted?
In 2007, the Fed’s assets were equal to 6.2 percent of nominal GDP and 8.3 percent of total commercial banking assets. To reach these same percentages, the Fed would have to shrink to $2 trillion in assets. This is not possible because the Fed’s assets must by definition be something greater than its currency outstanding, currently $2.4 trillion.
An essential mandate of the Fed, like all central banks, is to finance the government of which it is a part. Expanding its balance sheet is a way to force the commercial banking system to lend to the government. In 2007, the Fed’s assets were 9.7 percent of the national debt. To return to this level the Fed’s assets would need to fall to about $3.8 trillion, or be reduced by $2.9 trillion.
A reasonable target for the normalized size of the Fed might be a rounded to 10 percent of the national debt. The Fed’s assets would then be $3.9 trillion instead of $6.7 trillion. Since we know the Fed cannot sell its mortgage securities, however, to its allowed assets might be added its $2 trillion in mortgage securities, provided that these mortgage investments be put and kept in run-off until they reach zero again.
That would suggest a current shrinkage of the Fed to $5.9 trillion, or shrinkage of $800 billion plus however much the mortgage assets run off. Of course, in the next crisis, all bets are off and the Fed’s balance sheet may bloat once more.